If you receive a Notice of Bankruptcy, it will contain certain deadlines and meeting dates. The sample below shows where some of those deadlines will appear:
These dates are important because they limit what you can and cannot do in a case, and if you miss any of these deadlines you may have given up your rights to make certain objections or claims. You should read the Notice carefully to make sure you understand all of the information contained therein. To highlight some of these limits we have indicated them with red arrows in the sample Notice above.
Some of the important dates and limitations that appear on the Notice are as follows, in descending order as they appear on the Notice:
The date of filing: This is the date that the debtors case was filed with the court and some of the other dates will depend on this date.
The meeting of creditors: This is the date that the Section 341 Meeting of Creditors is first scheduled to take place. The Creditor's Meeting is scheduled about 30 to 45 days after the bankruptcy petition is filed. At least seven days before this meeting, the debtor is required to provide to the trustee and any creditor requesting it a copy of their most recently filed tax returns and proof of income for the most recent 90-day period.
The court-appointed Chapter 7 trustee will preside over this meeting. At the meeting, which the debtor is required to attend, the debtor will be asked to testify under oath as to the accuracy of the statements in the petition. Creditors have a right to attend this meeting and ask questions, though they are not required to.
Deadline to object to discharge or to challenge the dischargeability of certain debts:
A creditor may object to the discharge of amounts owed to them by the debtor under certain circumstances. If a creditor objects to the discharge of any of the debts listed in the petition or schedules, such objection must be raised within 60 days after the first scheduled §341(a) Meeting of Creditors. If you do not raise such an objection in a timely manner you risk waiving that right and having any such debt discharged.
Deadline to object to exemptions: Certain property claimed by the debtor to be exempt (not reachable by creditors), may be claimed as exempt in error. If that is the case, then that property might be used to pay creditors. Once the §341(a) Meeting is concluded, creditors only have 30 days to object to these exemptions after which the trustee may (and likely will) release all of this exempted property back to the debtor.
Deadline for financial management course: The debtor must take a financial management course within 60 days after the first scheduled §341(a) Meeting of Creditors, and if they don't they might not receive their discharge.
Automatic Stay: Immediately upon the filing date, an automatic stay prevents creditors from taking certain actions against the debtor. If you violate the automatic stay you may be subject to sanctions and fines by the bankruptcy court. You should ensure that you do not take any action against the debtor after the filing date without consulting with a bankruptcy attorney to ensure that you are not violating the automatic stay.
There may be other deadlines in cases that are different from the Chapter 7 no asset case in our example. For example, in a case with assets there will also be a deadline for filing a Proof of Claim. To ensure that you know all of the deadlines and meeting dates read your Notice carefully.
Once you understand what your deadlines are, the next step is to identify: What is your exposure to liability if the debtor receives their discharge?
Tuesday, October 23, 2012
Wednesday, October 17, 2012
What to do when you receive a Notice of Bankruptcy? Step 2: Are you a creditor?
If you receive a Notice of Bankruptcy you need to determine why you received the Notice. You might be a creditor, an interested party, or a codebtor. Creditors are not the only ones who receive a bankruptcy notice, and even if you're not a creditor you may have an interest in what happens in this bankruptcy case.
The Notice will not tell you why you received it. A sample notice, shown below, doesn't have your name anywhere on it. It does, however, have the name of the debtor and the case number. These two pieces of information should help you determine whether you are a creditor or some other interested party.
The Debtor, whose name is listed on our sample notice above as Sample Debtor, is the person who has asked the bankruptcy court for relief with their debts. If you are aware of a debt that the debtor owes you then you are a creditor and you should review the other information within that Notice. As a creditor you have certain rights that may include filing a Proof of Claim and attending the Meeting of Creditors.
If you're not sure if the debtor owes you money, then you might be a creditor or you might be something else, such as a contingent creditor, a co-debtor, or simply an interested party. To determine why you received this Notice, you must look at the schedules. The Bankruptcy court documents are public record and may be reviewed at the court or online if you have a Pacer access account. If you need help accessing these files any bankruptcy attorney will have an online account access and be able to look up the case file online.
Once you have access to the file, you will want to review the Bankruptcy Petition and Schedules to figure out where your name appears. If you are a creditor then your debt should be listed in one of the Schedules of Creditors.
If you are not a creditor you may still have an interest in the bankruptcy proceedings for some other reason. For example a codebtor (someone who is also responsible for a debt that the debtor owes) could be left being wholly responsible for a debt if the debtor is discharged of that debt. You might be a codebtor if you cosigned for a loan for the debtor, or if they cosigned for a loan that you took out, or if you borrowed money together for any reason (such as co-owners of a house with a mortgage). Codebtors are listed on the Schedule of Codebtors.
If you are not a codebtor or a creditor then your name may still appear somewhere else in the schedules, identifying why you received the Notice. For example, you may receive a Notice of Bankruptcy if you have a lease or other contract with the debtor, even if they are not behind on their payments. Reading all of the schedules carefully should help you discover why you received the notice, whether you are a creditor, codebtor or some other interested party.
Once you identify why you received the Notice, you can begin to evaluate what type of action you should take. For example the Notice tells creditors what many of their rights and obligations may be. The next step, therefore, is to identify: What are the important dates and deadlines I should keep in mind?
Thursday, October 11, 2012
What to do when you receive a Notice of Bankruptcy? Step 1: Identify the Chapter
If you receive a Notice of Bankruptcy, like the samples shown below, the first step is to identify what chapter the debtor is requesting relief under. There are multiple types of bankruptcy and each has different rules and requirements.
The title of the Notice identifies the Chapter that the bankruptcy is filed under. Below we have included samples from the two most common bankruptcies:
A Chapter 7 Notice for a no-asset case:
A Chapter 13 Notice for a payment plan case:
As you can see the title of the Notice identifies whether it is a Chapter 7 or Chapter 13 case. The notices differ as well in terms of the instructions they may provide because of the differences in these types of cases. Below we explain a little more about why the type of case matters. If you would like more information about bankruptcy visit our website.
The most common types of bankruptcy that you will encounter are Chapter 7, 11 and 13.
Chapter 7 Bankruptcy sometimes referred to as "liquidation", is designed for debtors in financial difficulty who do not have the ability to pay their existing debts. Chapter 7 is available to both individuals and businesses. Under Chapter 7 the debtor may claim certain property as exempt under the governing law. A trustee may have the right to take possession of and sell the remaining property that is not exempt and use the sale proceeds to pay your creditors. After liquidation of these non-exempt assets, all remaining qualified debts are then discharged and the creditors are out of luck.
Chapter 11 Bankruptcy sometimes referred to as "reorganization", is designed for debtors in financial difficulty who may have the ability to pay their existing debts in part. Chapter 11 is available to both individuals and businesses, though is more typical for businesses. Under Chapter 11 the debtor must propose a plan that results in more payments to debtors than they would get under a liquidation. The plan must be approved by a council of creditors.
Chapter 13 Bankruptcy involves the repayment of all or part of the debts of an individual with regular income. Chapter 13 is designed for individuals with regular income who desire to pay their debts in installments over a period of time. Debtors are only eligible for Chapter 13 if your debts do not exceed certain dollar amounts set forth in the Bankruptcy Code. Under Chapter 13, the debtor must file with the Bankruptcy Court a plan to repay their creditors all or part of the money they owe, using future earnings. The period allowed by the court to repay the debts may be three (3) to five (5) years. The court must approve the plan before it can take effect.
Our next post will address the following step for identifying what you should do with this notice after you have identified the type of bankruptcy: Are you actually a creditor, or did you receive the Notice for some other reason?
Monday, October 8, 2012
A Step-By-Step for Bankruptcy Creditors: What to do when you receive a Notice of Bankruptcy.
If you receive a Notice of Bankruptcy, like the sample shown below, you should ensure that you know why you received it and what your rights are. The first step is to read the Notice. It contains much of the information you need to know, as well as instructions on what to do if you wish to respond.
Receiving a Notice such as this one, likely means that you are a creditor and the debtor is trying not to pay the debt they owe you. But you may have remedies if you take action and know your rights.
Over the next series of posts we will help you understand the steps you should take when you receive a Notice of Bankruptcy. The questions you need answered include:
What kind of Bankruptcy is it (most likely options include 7, 11 and 13)?
Are you actually a creditor, or did you receive the Notice for some other reason?
What are the important dates and deadlines I should keep in mind?
What is your exposure to liability if the debtor receives their discharge?
Should you hire a bankruptcy attorney to help you evaluate your claims?
Once you answer these questions you will be prepared to respond to the Notice of Bankruptcy, appropriately.
Wednesday, October 3, 2012
Professional Athletes and Bankruptcy: Symptoms of a bigger problem.
ESPN aired "Broke" last night, a documentary in their 30 for 30 series, which highlighted the financial problems that many professional athletes face. While it may be difficult to feel bad for people who earn in one game check more than most of us earn in one year, the reality is that the same traps that lead to most consumer bankruptcies are exaggerated by the big paychecks that professional athletes receive at a young age.
The consumer culture of America glorifies spending over saving, and youth are at the greatest risk for falling into that trap. Spending and creating debt on a larger scale by professional athletes gets out of hand in the same way that those habits bury the average individual.
Even living within your means when you have a job is not enough of a plan to reach the goals of safe retirement and ensure staying out of bankruptcy. If you don't save as well, you won't have a safety net in the event of injury, unemployment, or other unexpected events. The reason that bankruptcy is so likely among professional athletes is because injury and retirement at a young age are almost guaranteed in that business.
But you can learn from their mistakes by budgeting realistically, and having a plan for disability and retirement. Even if you've found yourself in a position to file bankruptcy once, you can learn from that experience and use your fresh start to plan for your goals this time around.
In "Broke", Herman Edwards, a former NFL player and coach, was interviewed. He speaks at the NFL rookie seminar about the importance of financial planning and in his interview he pointed out that "a goal without a plan is a wish."
So are you wishing, or planning?
Wednesday, September 5, 2012
Can bankruptcy help with my student loans?
Student loans have become a larger and larger portion of the average consumer's debt. As a country, our student loan debt is now higher than consumer spending debt. While consumer spending debt can typically be discharged in a bankruptcy, though, most student loan debt cannot.
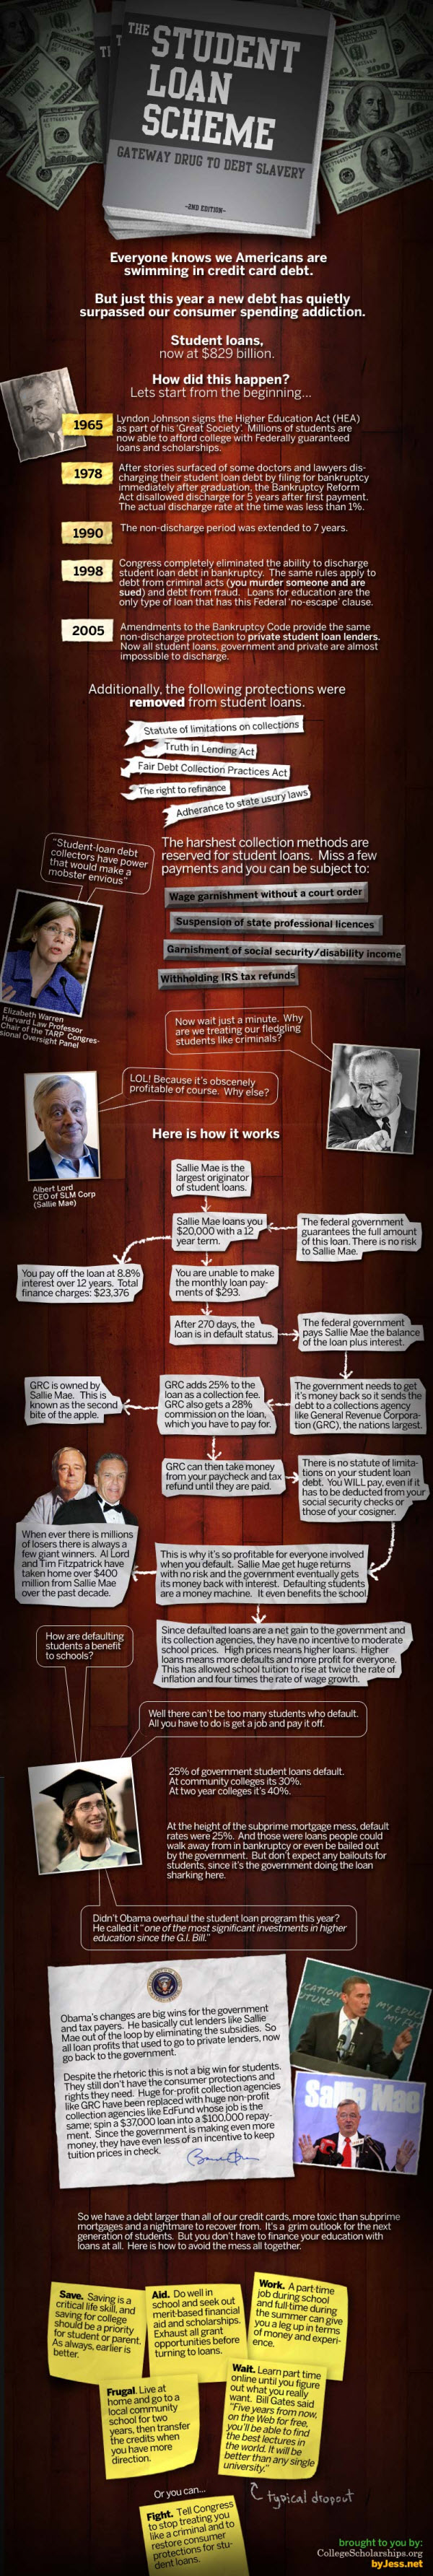
As described in this infographic, student loan debt is exempt from many of the protections that consumers have available when it comes to other debts. If that seems unfair to you, then you're not alone. A few of our fellow legal bloggers have written some compelling posts on the necessity of changing the law on bankruptcy when it comes to student loans, and even the president has weighed in in favor of making a change.
However, until the law is changed, the current status is bleak for most. While a Chapter 13 plan can help you structure the payments and potentially stop wage garnishments, it will not reduce the overall debt, and at the end of the plan you may be back in the same position. In a Chapter 7, student loans are considered a non-dischargeable debt unless you can show "undue hardship." In the Brunner case, the U.S. Court of Appeals 2nd Circuit admits that that their is little help in the statute for defining what constitutes an "undue hardship."
The Court in that case required a three-part test to show undue hardship:
"(1) that the debtor cannot maintain, based on current income and expenses, a "minimal" standard of living for herself and her dependents if forced to repay the loans;
(2) that additional circumstances exist indicating that this state of affairs is likely to persist for a significant portion of the repayment period of the student loans; and
(3) that the debtor has made good faith efforts to repay the loans."
Essentially this means that to discharge the debt you have to show that you can't pay the loan now, you tried to pay the loan, and it is not likely you will be able to pay the loan before you die. Many believe this test limits the benefits of the "undue hardship" clause to the elderly or terminally ill.
For most, the best option may not be bankruptcy at all, at least not to deal with student loan debt. Until and unless the law changes, the Income Based Repayment Plan available through the Department of Education is the only option for reducing the burden of student loans when a partial financial hardship exists.
If you still think this is unfair, tell congress that you want it changed.
The Student Loan Problem (Infographic)
The following infographic provides an overview of the student loan problem in America, how we got here, and why it is getting worse:

Infographic by College Scholarships.org
Reprinted from: College Scholarships.org
Kelsey & Trask, P.C. provides this graphic for informational purposes only. We do not endorse nor claim endorsement from the source site or organization. Kelsey & Trask, P.C. is not responsible for any information contained therein, unless indicated specifically on that site.
Subscribe to:
Posts (Atom)