Showing posts with label debt. Show all posts

Wednesday, September 5, 2012

Can bankruptcy help with my student loans?

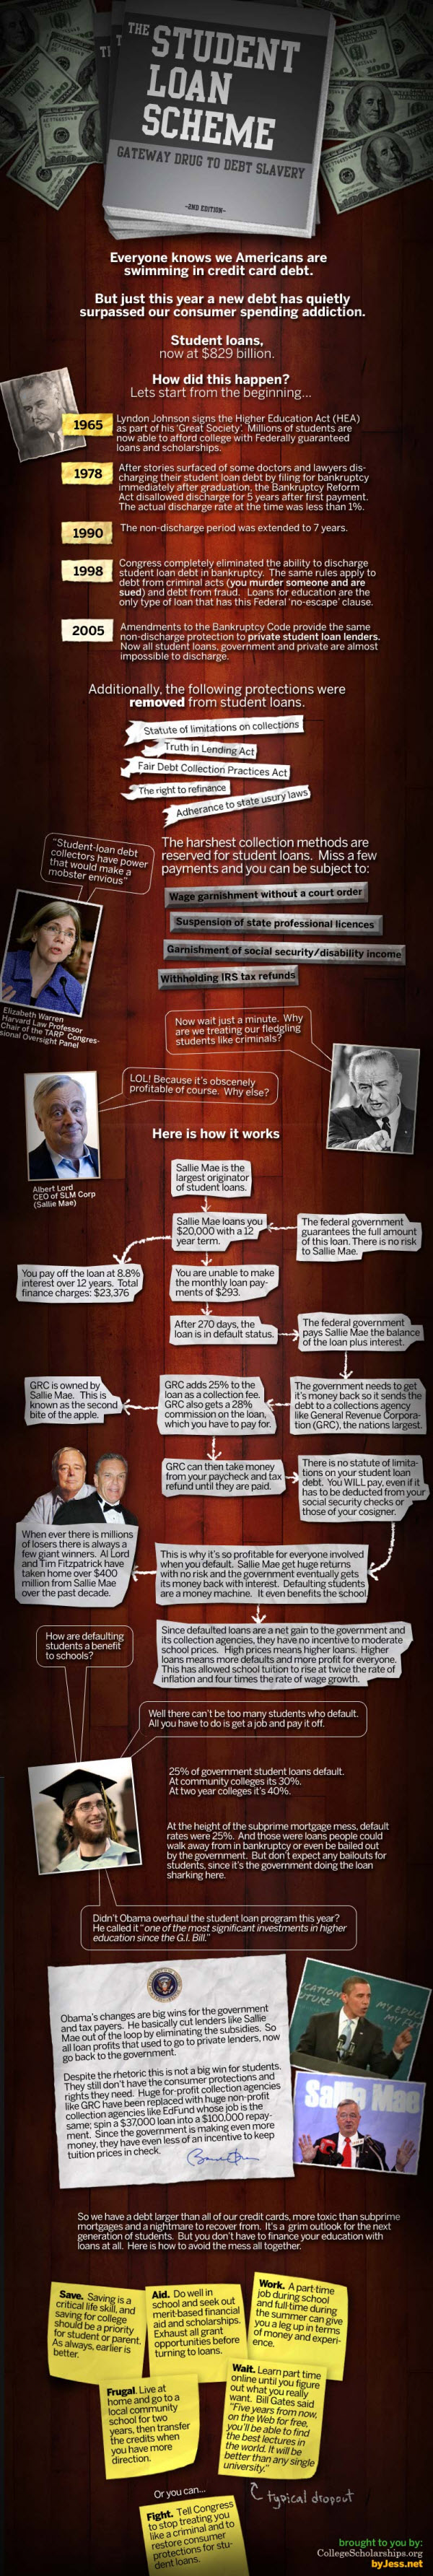
Student loans have become a larger and larger portion of the average consumer's debt. As a country, our student loan debt is now higher than consumer spending debt. While consumer spending debt can typically be discharged in a bankruptcy, though, most student loan debt cannot.

As described in this infographic, student loan debt is exempt from many of the protections that consumers have available when it comes to other debts. If that seems unfair to you, then you're not alone. A few of our fellow legal bloggers have written some compelling posts on the necessity of changing the law on bankruptcy when it comes to student loans, and even the president has weighed in in favor of making a change.

However, until the law is changed, the current status is bleak for most. While a Chapter 13 plan can help you structure the payments and potentially stop wage garnishments, it will not reduce the overall debt, and at the end of the plan you may be back in the same position. In a Chapter 7, student loans are considered a non-dischargeable debt unless you can show "undue hardship." In the Brunner case, the U.S. Court of Appeals 2nd Circuit admits that that their is little help in the statute for defining what constitutes an "undue hardship."

The Court in that case required a three-part test to show undue hardship:

"(1) that the debtor cannot maintain, based on current income and expenses, a "minimal" standard of living for herself and her dependents if forced to repay the loans;

(2) that additional circumstances exist indicating that this state of affairs is likely to persist for a significant portion of the repayment period of the student loans; and

(3) that the debtor has made good faith efforts to repay the loans."

Essentially this means that to discharge the debt you have to show that you can't pay the loan now, you tried to pay the loan, and it is not likely you will be able to pay the loan before you die. Many believe this test limits the benefits of the "undue hardship" clause to the elderly or terminally ill.

For most, the best option may not be bankruptcy at all, at least not to deal with student loan debt. Until and unless the law changes, the Income Based Repayment Plan available through the Department of Education is the only option for reducing the burden of student loans when a partial financial hardship exists.

If you still think this is unfair, tell congress that you want it changed.

The Student Loan Problem (Infographic)

The following infographic provides an overview of the student loan problem in America, how we got here, and why it is getting worse:

Student Loans Scheme.
Infographic by College Scholarships.org

Reprinted from: College Scholarships.org

Kelsey & Trask, P.C. provides this graphic for informational purposes only. We do not endorse nor claim endorsement from the source site or organization. Kelsey & Trask, P.C. is not responsible for any information contained therein, unless indicated specifically on that site.

Thursday, May 31, 2012

I am the primary borrower on a loan and my cosigner has filed for bankruptcy. What should I do to protect myself?

A co-signer is an individual who is promising to repay a loan in the event the primary borrower defaults. In many cases, having a co-signer on a loan may have been necessary to obtain the loan because the primary borrower’s credit rating was insufficient to qualify on their own, and the co-signer stepped in to assist the primary borrower to obtain financing.

As we discussed in our previous post, if the primary borrower defaults (or files bankruptcy), the co-signer will be required to pay the loan back. But what about the reverse situation?

How is the primary borrower affected if the cosigner files for bankruptcy?

Consider the same example: Adam wants to buy a car, but can only qualify for a loan with a co-signer. Betsy agrees to co-sign, but her name is not listed on the title as an owner of the vehicle. This time Betsy files for bankruptcy and obtains a discharge of the car loan. For the sake of simplicity, we will assume that Betsy has no ownership in the vehicle that may be attributed to her by the Trustee.

Adam is still legally obligated to repay the unpaid balance of the loan. However, when Adam pays off the loan, all liens will be released, and the title will be issued in Adam’s name. Most auto financing agreements make no distinction between the “borrower” and “co-borrower” aside from whose name the title will ultimately be issued to. As such, the bankruptcy of a co-borrower is similarly a breach of the terms of the loan, and could result in a default under the terms of the note. As before, the bankruptcy (and discharge) of the co-borrower’s obligation leaves the lender in a position where they can only pursue one individual, not two, in the event the loan is not paid.

This material departure from the original agreed upon terms could be considered a default, and in fact, many auto financing agreements specifically include such a term. However, it has been my experience that the lender will receive a greater financial return by accepting the primary borrower’s monthly payments than they would by repossessing the vehicle and selling it at auction, meaning that the primary borrower will likely keep the vehicle, despite the co-borrower’s bankruptcy.

In the event a co-borrower files for bankruptcy, the best thing that the primary borrower can do is seek to refinance the balance on the car loan, if possible. Many credit unions and some larger banks offer automobile refinancing loans. By refinancing the loan, the primary borrower has effectively paid off the loan securing the vehicle, and negated any circumstances which could trigger a default. If handled properly, and for a qualified borrower, it is often possible to keep payments the same, or even lower payments upon refinancing the car.

A borrower may be tempted to sign a reaffirmation agreement presented by the lender. However, executing the reaffirmation agreement is, in my opinion, not a legal guarantee that the bank will take no further action, nor will it cure any default under the terms of the note upon the co-borrower’s filing for bankruptcy. First, in order to cure the issue of default, at a minimum, the co-borrower filing for bankruptcy would have to sign. A reaffirmation agreement is an agreement arising in the context of a bankruptcy case. Here, the primary borrower is not seeking bankruptcy protection, nor is he electing to “remove” the debt from the discharge order; and therefore the primary borrower, Adam in our example above, has no standing to sign the reaffirmation agreement.

The bankruptcy of a co-borrower should not appear on Adam’s credit report, but because some lenders will automate their reports to credit agencies, there is a reasonable likelihood that the entry may make some indication of bankruptcy. If this happens, the information in the credit report is incorrect. It may be necessary to contact the three credit bureaus (Equifax, Experian, and Trans Union) as well as the lending institution to ensure that this information is correctly reported on the primary borrower’s credit report. Again, refinancing with a new loan is the simplest way to resolve this issue because then the loan will be listed as paid, and the new loan will report positively on a credit report (as long as you continue to pay it on time).

As with the decision to co-sign a loan, the decision to obtain a loan requiring a co-signer comes with significant legal consequences if the co-signer does not honor the terms of the note. Consider the need to take out a loan with a co-signer carefully, and if the co-signer files for bankruptcy , it may be worth your while to reach out to a bankruptcy attorney to better understand your options and obligations regarding the loan.

I co-signed a loan and the primary borrower has filed for bankruptcy. What should I do to protect myself?

A co-signer is an individual who is promising to repay a loan in the event the primary borrower defaults. In many cases, having a co-signer on a loan may have been necessary to obtain the loan because the primary borrower’s credit rating was insufficient to qualify on their own, and the co-signer stepped in to assist the primary borrower to obtain financing without considering the long-term ramifications of that decision.

If the primary borrower defaults (or files bankruptcy), the co-signer will be required to pay the loan back. Additionally, unless the co-signer is also a “co-purchaser”, the co-signer is burdened only with the responsibility of repaying the debt and receives none of the benefit of the loan.

Consider the following example: Adam wants to buy a car, but can only qualify for a loan with a co-signer. Betsy agrees to co-sign, but her name is not listed on the title as an owner of the vehicle. Adam files for bankruptcy, and surrenders (gives back the car to the lender) and obtains a discharge of the car loan. Betsy is still legally obligated to repay the unpaid balance of the loan, but does not get title to the car when she finally finishes paying off the car – which now belongs to the bank.

Being a co-signer can be extremely risky, and if the primary borrower files for bankruptcy, your credit can be affected. However, you can manage the credit damage by doing the following:

1. Determine whether the primary borrower intends to reaffirm the debt in bankruptcy court, (i.e., keep the car and continue paying the loan), or will surrender it back to the lender.

2. If the primary borrower is going to reaffirm the vehicle, ensure that they keep the payments current through bankruptcy, and sign the reaffirmation agreement.

3. If the primary borrower is not intending to reaffirm, or has already lost the vehicle due to repossession, the only way to protect your credit is to repay the loan pursuant to the terms of the agreement

4. Be aware that many loans include an acceleration clause, meaning that if one of the borrowers files bankruptcy, the entire balance of the loan is due. If the lender exercises their right to accelerate the loan, the co-signer may not be able to make regular monthly payments.

Remember, the decision to co-sign a loan is often made out of a desire to help a friend or family member, but it comes with significant legal consequences if they fail to repay. Consider any request to co-sign a loan carefully, and if the primary borrower files for bankruptcy , it may be worth your while to reach out to a bankruptcy attorney to better understand your options and obligations regarding the loan.

Thursday, April 12, 2012

I’m suing someone and they filed for bankruptcy. What happens next?

As we have discussed in previous posts, immediately upon filing a voluntary Petition for Bankruptcy, the protections of the Automatic Stay go into effect to protect the debtor in an active bankruptcy. 11 U.S.C. §362(a) provides that the commencement or continuation of any acts or proceedings against the debtor in an effort to collect or recover any debt is automatically stayed, and any further efforts at collection are prohibited and punishable by law. Pursuant to 11 U.S.C. §362(k), an individual injured by any willful violation of a stay provided by this section shall recover actual damages, including costs and attorneys’ fees, and, in appropriate circumstances, may recover punitive damages.

Therefore, if you are the plaintiff in a civil lawsuit against a debtor in bankruptcy, it is imperative that you immediately cease collection efforts against the debtor, including ensuring the court takes no further action with respect to the case. Debtor’s counsel should file a “Suggestion of Bankruptcy” with the court, which is a notice to the Court that a party to the case is in bankruptcy, and the case may not proceed with respect to them or any claims against them. If the Debtor’s counsel does not file a suggestion of bankruptcy, in order to avoid the penalties of 11 U.S.C. §362(k), you or your attorney should ensure the court is aware that a party to the case has filed for bankruptcy. The Court Clerk or your civil attorney will advise you on the proper way to file such a notice.

Once the case has been stayed (i.e., paused), you must decide if you have grounds to pursue your claims in bankruptcy court, or have a reason why the particular debt is nondischargable by law in bankruptcy. For example, debts which were obtained by false pretenses, or false representations, or actual fraud are not dischargeable, nor are debts owed for fraud or defalcation while acting in a fiduciary capacity, or embezzlement or larceny, among other things. Each of these categories have particular legal requirements in order to prove nondischargability, and in order to prevent the discharge of that debt, you will need to prepare and file an Adversary Proceeding in the Bankruptcy Court.

Procedurally, an Adversary Proceeding is conducted much like a lawsuit in District Court or Superior Court, although the Bankruptcy Court maintains jurisdiction over the resolution of the claims. Removing a case to bankruptcy court can have far-reaching consequences on other aspects of the litigation, and we strongly recommend you consult with an attorney before doing so.

In some situations where your debt is secured or enjoys a legal priority over other debts, and there are assets available in the bankruptcy to pay creditors, it may not be necessary to file an adversarial proceeding, but rather a Proof of Claim. A Proof of Claim is your notice to the court establishing the existence of a debt and the nature of the debt, and will be reviewed by the Trustee and the debtor’s counsel. If funds are available to satisfy your class of debt, you may receive payment (partial or full, depending on the assets obtained from the debtor) from the bankruptcy trustee on behalf of the debtor’s bankruptcy estate.

Regardless, if you are involved in litigation and the opposing party files for bankruptcy, contact Attorney Matthew P. Trask to discuss how the bankruptcy will affect your case and claims moving forward. To fail to assert your rights in the bankruptcy case so could be an extremely costly mistake.


Monday, April 9, 2012

I’m being sued. Can a bankruptcy help?

If you are being sued on a debt collection matter, or other civil matter for which a money judgment can be imposed, filing bankruptcy may give you relief from your creditors. The Automatic Stay halts all existing court proceedings that the debtor is involved in, as well as any collection efforts for the individual's debts, until the bankruptcy proceedings are resolved.

In certain situations, the Automatic Stay might not prevent other court proceedings from continuing, at least in part. For example, in any family law case involving child support and custody, issues involving visitation or current child support are not subject to the Automatic Stay, but issues involving past due child support will be continued until the Automatic Stay is lifted at the end of bankruptcy proceedings.

The Automatic Stay is designed to provide some breathing room for the debtor in bankruptcy and provide the time and logistical ability to reorganize debts (as in a Chapter 11 or Chapter 13), or obtain a discharge (as in a Chapter 7 case). While the long-term resolution of a lawsuit will depend on the type of case, the Automatic Stay will provide some immediate protection for the debtor.

Ultimately, the debtor’s primary concern will be whether the debt or obligation on which the lawsuit is based will be discharged in bankruptcy. Absent fraud or certain other factors, most lawsuits arising out of consumer debts (e.g., lawsuits on unpaid credit cards or mortgage deficiencies following a foreclosure) are dischargeable under Chapter 7, and can be discharged following the successful completion of a Chapter 13 plan. However, the following debts arising under some suits cannot be discharged:

  1. Lawsuits for unpaid taxes, custom duties, or debts to pay taxes or custom duties.
  2. Lawsuits collecting student loan debt.
  3. Lawsuits to collect unpaid spousal or child support.
  4. Lawsuits filed by a spouse, former spouse, or child to enforce a Court Order obtained in a domestic relations proceeding.
  5. Lawsuits where the debt was included in a previous bankruptcy wherein discharge of that particular debt was waived, such as reaffirmed debts.
  6. Lawsuits for debts owed for money, property, services, or refinancing of credit, if obtained by false pretenses, or false representations, or actual fraud.
  7. Lawsuits involving consumer debts for luxury goods obtained within ninety (90) days of the date of filing of the bankruptcy petition.
  8. Lawsuits involving cash advances obtained within seventy (70) days of the date of the filing of the bankruptcy petition.
  9. Lawsuits involving debts owed for fraud or defalcation while acting in a fiduciary capacity, or embezzlement or larceny.
  10. Debts owed for fines, penalties, or forfeitures payable to and for the benefit of governmental entity.
  11. Lawsuits and debts owed for death or personal injury arising from the operation of a motor vehicle, boat, or aircraft while intoxicated by drugs or alcohol.

It is important to understand that the filing of a case will temporarily stop the lawsuit for many of the above claims, even though the actual debt is nondischargable. However, once the protections of the Automatic Stay expire, or the opposing party obtains permission from the Bankruptcy Court to move ahead, the case may proceed, and you may be required to pay any debt arising out of the above types of lawsuits, even after bankruptcy.


Monday, August 29, 2011

FAQ #10: Do I have to include all my bills when I file bankruptcy?


Yes. Every debt you owe must be completely and accurately disclosed in the documents filed to commence your bankruptcy case. Bankruptcy is not a "pick and choose" proceeding. You cannot not put some debts in and leave other debts out. Intentionally omitting debts from your bankruptcy case may result in the nondischargability of those debts, the dismissal of your bankruptcy case, fines, or imprisonment for bankruptcy fraud.

If you don't see your question and would like more information please do not hesitate to call us at 508.655.5980, e-mail us, or attend one of our weekly Free Debt Relief Clinics.

Friday, July 1, 2011

Staying out of Financial Trouble: Let the Joneses Do Their Own Thing

This planet has — or rather had — a problem, which was this: most of the people living on it were unhappy for pretty much all of the time. Many solutions were suggested for this problem, but most of these were largely concerned with the movement of small green pieces of paper, which was odd because on the whole it wasn't the small green pieces of paper that were unhappy. - The Hitchhiker's Guide to the Galaxy
Everyone has heard the expression "Keeping up with the Joneses". Many of us consciously or subconsciously compare ourselves to our peers, and use the transfer of wealth (i.e., buying the things that impress others or help us fit into a particular social circle) to keep us happy in our own peer group.

As you are considering a financial reorganization through a debt payment plan or bankruptcy, it is important to identify the risks that will derail your efforts, or worse yet, put you back in the same place you were in prior to bankruptcy or debt relief. One hidden trap is pressure to "keep up with the Joneses" or engage in "retail therapy". While it may be difficult to completely curtail your spending in some of these areas, a recent Bankrate.com article "Are Your Friends Making You Broke" discusses some ways to identify harmful spending habits and suggests some useful alternatives.

Some suggestions:

1. Remember your true friends want what's best for you. Discuss your financial goals with them to alleviate some of the social pressures.

2. Consider the long-term costs and expenses of that expensive new item you have your eye on.

3. Suggest less-expensive alternatives when asked to participate in an activity you cannot truly afford.

4. Consider alternative products and technology that will give you the convenience and functionality, but at a fraction of the price. Sure, GPS-enabled smartphones are great, but asking for directions or a trusty map will get you there too.

Getting and staying out of debt isn't easy, but it can done if you stick to a plan. If you need help working out a plan, the debt relief attorneys at Kelsey & Trask, P.C. are always ready to help.

Friday, March 11, 2011

Bankruptcy and Taxes: Does a Bankruptcy affect Cancellation of Debt Income?

With the housing market collapse and the rise in short sales and foreclosures, many former homeowners are faced with the consequences of left-over debt from their mortgage. While deficiency judgments will force many into bankruptcy, there are also problems when the debt is forgiven in the form of cancellation of debt income.

What is cancellation of debt income? Generally, debt that is forgiven by a lender creates tax consequences for the debtor – the lender issues a 1099-C on the cancelled debt, and the IRS considers the cancelled debt as income to the debtor. However, there are exceptions to this rule, and, depending on the circumstances, cancelled debt may not create any tax liability, even if the debtor is no longer required to pay the debt. This (rather lengthy) article discusses the impact of bankruptcy on cancelled debt. (Note: The IRS Code has other exemptions that may apply and eliminate some or all tax liability on cancelled debt, such as The Mortgage Forgiveness Debt Relief Act or the insolvency exception to cancelled debt income. These exceptions are beyond the scope of this article, and will be addressed separately in future posts.)

Scenario 1: You file for bankruptcy, and receive a discharge of your dischargeable consumer debts. Are you required to pay taxes on the debt that was discharged in the bankruptcy?

Answer: No. According to 26 U.S.C. § 108(a)(1)(A):

Gross income does not include any amount which (but for this subsection) would be includible in gross income by reason of the discharge (in whole or in part) of indebtedness of the taxpayer if—

(A) the discharge occurs in a title 11 case [i.e., Bankruptcy],
(B) the discharge occurs when the taxpayer is insolvent,
(C) the indebtedness discharged is qualified farm indebtedness,
(D) in the case of a taxpayer other than a C corporation, the indebtedness discharged is qualified real property business indebtedness, or
(E) the indebtedness discharged is qualified principal residence indebtedness which is discharged before January 1, 2013.

Therefore, as long as the debt was properly discharged in bankruptcy, the cancelled debt will not create any taxable events for the debtor.

Scenario 2: You have your house listed in a short sale, which the bank approves. Unfortunately, other factors ultimately require that you file bankruptcy. After you file (or after you receive your discharge), the mortgage lender sends you a 1099-C for the cancelled debt income of the forgiven balance of the mortgage. Do you have to pay taxes on the cancelled debt income?

Answer: No. As above, since the discharge of the underlying debt (the first mortgage, in the example above) occurs in a bankruptcy case, 26 U.S.C. § 108(a) applies. In this case, the code requires that the amount of the debt, although “forgiven” by the mortgage lender, was discharged in bankruptcy, and therefore, excluded from the debtor’s gross income.

Scenario 3: You are attempting to avoid bankruptcy, and have your house listed in a short sale. The bank approves the short sale, and you are hoping that your real estate attorney will be able to convince your lender to “forgive” the deficiency. The lender does in fact forgive the deficiency, and sends you a 1099-C for the cancelled debt income of the forgiven balance of the mortgage. Unfortunately, other factors (such as a second mortgage that will not be “forgiven” or credit card debt) ultimately require that you file bankruptcy. Do you have to pay taxes on the cancelled debt income?

Answer: Scenario 3 creates a question of timing. Here, the difference between this example and the example above is that the lender “forgave” the debt and issued a 1099-C before the debtor filed a bankruptcy case. This raises the question as to whether the debt was legally cancelled by the lender, and therefore could not have been discharged in bankruptcy.

So, then, the question becomes: “Can a bankruptcy filing discharge debt that has already been forgiven, in order to avoid the tax consequences of cancellation of debt income?”

The mere fact that a creditor has issued a 1099-C is not, in and of itself, an admission by the creditor that it has released the debt and can no longer pursue collection, nor does a 1099-C legally discharge the debtor from liability of the debt that is described on Form 1099-C. See In re: Zilka, 407 B.R. 684, 688-689 (2009).

Zilka was not the first time the Court was required to address this issue, and specifically stated in its ruling:

The Internal Revenue Service, which regulatory agency is the one that promulgated 26 C.F.R. § 1.6050P-1, and whose interpretation of the same is thus entitled to great deference (citation omitted), does not view a Form 1099-C as an admission by the creditor that it has discharged the debt and can no longer pursue collection [thereon]. See 2005 WL 3561135 at 689 (Dec. 30, 2005).
***
Forms 1099-C, as a matter of law, do not themselves operate to legally discharge debtors from liability on those claims that are described in such Forms 1099-C. See Owens v. Commissioner, 67 Fed.Appx 253, ___, 2003 WL 21196200 at 3 (5th Cir.2003) (issuance and filing of Form 1099-C does not constitute actual cancellation of the loan).
***
Form 1099-C…only serves to report (strictly for tax purposes) information regarding an event that has already happened, which reporting of information cannot possibly be stretched or strained to also constitute a present contractual agreement not to sue, or a present contractual renunciation of rights against, a debtor. See Leonard v. Old National Bank Corp., 837 N.E.2d 543, 545-546 (Ind.Ct.App.2005) (filing a Form 1099-C is merely an informational filing with the I.R.S., done to report an event that has already happened, and thus does not operate to cancel debt itself).

See In re: Zilka, 407 B.R. 684, 688-689 (2009). See also IRS Publication 4681.

Based on the above precedent, even if a lender issues a 1099-C prior to a bankruptcy filing, the issuance of the 1099-C does not serve to legally discharge the debt. If that debtor then files bankruptcy, they should then include that debt on their bankruptcy schedules to ensure that it is discharged. And as long as the debtor included the underlying debt in the debtor’s bankruptcy case (and ultimately received a discharge of that debt), 26 U.S.C. § 108 applies, and the mere issuance of the 1099-C prior to the bankruptcy case, the cancelled debt will not create any taxable events for the debtor.

Finally, when a lender issues 1099-C, even if no tax is due, the debtor should discuss this issue with a CPA to ensure that his tax returns are properly filed to exempt the 1099-C income from the debtor’s gross income.

If you have any questions regarding the tax consequences of bankruptcy, contact Attorney Matthew P. Trask to schedule an initial one-hour consultation. Attorney Trask would like to thank Kathryn Collins, Esq. and Jason Cooper, CPA for their assistance in preparing this article, and would also like to thank Mark Tanney, Esq., a Maryland Bankruptcy Attorney, for his insights which inspired this article.

Tuesday, February 8, 2011

4 Facts Your Divorce Attorney Should know about Bankruptcy? Fact #3: Jurisdiction over Your Debts

The Divorce Court has the power to divide not just assets, but also debts. Just as the Court can assign the property titled to one spouse to the other spouse if the equities require, the Court can also order one spouse to pay the debts of the other spouse. But the Bankruptcy Court has the power to discharge debts. So what happens if the Divorce Court orders a spouse to pay a joint credit card debt, but the Bankruptcy Court gives that same spouse a discharge of that debt.

For purposes of this example, let's assume that the Husband and Wife were each ordered to pay half of a joint credit card debt. The Wife then files for bankruptcy and the credit card debt is discharged. Both the Husband and Wife were liable for the whole debt to the credit card company, but now only the Husband is liable to the credit card company. If the payment ordered by the divorce court is not categorized as a domestic support obligation (discussed in our next post) then the Wife no longer owes the debt to the credit card company or the Husband, and the Husband is left having to pay the entire debt.

It is possible for Separation Agreements or Divorce Judgments to avoid this problem by using assets to pay (or offset) debts, instead of trying to reassign debts. If enough assets are not available to do this then payments such as alimony, which are domestic support obligations, can be used instead to accomplish this same goal and avoid the discharge problem.

This issue can be further complicated when the debt that is at issue is a mortgage or secured debt. In order to avoid costly mistakes for divorce clients, we encourage divorce practitioners to consult with bankruptcy counsel when there is the potential that one party in the divorce will file for bankruptcy.

Click here to read Fact #2: Domestic Support Obligations.

Tuesday, February 1, 2011

Should damage to my credit keep me from filing bankruptcy?

Assuming your bankruptcy goes to discharge without objection, you will now find yourself with the daunting task of rebuilding your credit, post-bankruptcy. A Bankruptcy appears on your credit report and will negatively impact your credit score. Because bankruptcy negatively impacts your credit, borrowing money may be more difficult, and when possible, may be more expensive.

A bankruptcy filing remains on your credit report for 10 years, and individual debts discharged in bankruptcy for 7 years following your discharge. Therefore, whenever you apply for credit, a new loan, or undergo a background check, a previous bankruptcy will be visible to the loan officer, hiring manager or credit card company.

But what is the alternative?

If you have a significant amount of debt and can't make the payments then your credit is already damaged. If you are making the payments but can only make the minimum payments, then you may be able to save your credit but only if you are able to find a way to pay down your debts.

A good guideline for deciding if you are a potential candidate for bankruptcy is to consider how long it will take you to pay down your debts. If you make a realistic budget of all of your income and expenses and pay all of your excess income towards your debts, how long will it take you to pay them off? If the answer is five or more years, then you may be a good candidate for bankruptcy and should consult with an attorney to find out more about your options.

As long as you cannot pay down your debts you won't be able to borrow or use your credit anyway, so filing bankruptcy may be a better alternative. This is especially true if you are only paying minimum payments and have no realistic chance of paying down your debts in the foreseeable future.

How filing (or not filing) affects your credit is only one factor in making a decision about whether or not to file a bankruptcy and you should consider how your credit might be affected by your debts regardless of whether or not you file a bankruptcy.

Monday, January 18, 2010

What do those "Debt Relief Agencies" Do? Do they work?

It seems every time you turn on the radio, TV, or go online, you see stories of individuals in financial trouble, and plenty of businesses, agencies and organizations offering to help them out. Recently, one particular “debt relief agency” has touted its “quick fix” services by encouraging consumers to stop paying their credit cards and “not more money to those greedy banks”. The service then promises to work with consumers to resolve their debt for “pennies on the dollar”. So, do debt relief companies such as the one described deliver on their promises?

Most debt relief companies operate like so: You pay them a flat fee, usually calculated as a percentage of your total debt, and sign a power of attorney over to the debt agency allowing them to “negotiate with your creditors”. You are then told to stop paying your credit cards. After you have stopped paying the minimum balances, credit card companies begin collection action against you, and may refer your case to a collection agency. Afterward, the “debt relief agency” will step in and make a lowball offer to the collection agency or creditor, which the credit card company may or may not accept.

I have received a number of calls recently from consumers that have paid “debt relief agencies” thousands of dollars to assist them in resolving credit card debt, only to find themselves in a far worse position: liens on property, wage garnishments, even foreclosure. The fact of the matter is that word is getting out about debt relief agencies, and more and more lenders are becoming unwilling to settle with the individual debtors, and rather seek resolution in court or through foreclosure. In most cases, the debt relief agencies are not licensed to practice law, so as soon as a debt collection lawsuit or foreclosure proceedings are commenced, the consumer is left high and dry, still in debt and hundreds or thousands of dollars out of pocket.

The success of any debt relief agency is completely dependent upon the creditor’s willingness to settle the debt at a fraction of what is owed. There is no obligation of a creditor to accept a settlement offer or reduce your debt to any amount other than what is actually owed. Bankruptcy is different, and in a bankruptcy case the Bankruptcy Court is essentially ordering the discharge of certain debts and does not rely on a third party’s ability to settle a case. However, only the United States Bankruptcy Court can compel the discharge of certain debts, and only if the laws and procedures for filing bankruptcy are followed. Bankruptcy is not the only option (or even the first or best option) to overcoming a financial problem, but it may play an important part in the debtor’s strategy, and in certain circumstances, be the last and best option for a fresh start.

Monday, December 14, 2009

Under What Circumstances Can Creditors Object to the Discharge of a Debt?

A creditor may object to the discharge of amounts owed to them by the debtor under certain circumstances. If a creditor objects to the discharge of any of the debts listed in your petition or schedules, such objection must be raised within 60 days after the first scheduled §341(a) Meeting of Creditors. Alternatively, the trustee must move to dismiss your case within the 60-day period following the §341(a) Meeting of Creditors if he or she finds that the granting of relief would be an abuse of the provisions of Chapter 7.

If you incurred new debt of $500.00 or more for "luxury goods or services" within the 90-day period before your bankruptcy, or if you obtained a cash advance from a credit card or other loan in the amount of $750.00 or more within the 70-day period before your bankruptcy filing, that debt is presumed to be non-dischargeable, absent the debtor's showing to the contrary.

A creditor may object to your request to discharge a debt if the debt was obtained or incurred as a result of fraud, embezzlement or larceny, or any willful or malicious injuries you have caused others. If the Creditor establishes by a preponderance of the evidence that the debt was obtained by any of the above means, the debt will be deemed non-dischargeable.

Creditors may object to the discharge of certain debts if you have concealed or destroyed any property or financial records; made any false statements in connection with incurring a debt or other financial obligation; withheld financial or other material information; failed to explain losses; failed to respond to material questions permitted under the Federal Rules of Bankruptcy Procedure; or if you were granted a discharge with respect to that debtor in a prior bankruptcy case filed within the last 6 years.

Thursday, November 19, 2009

Financial Crisis? You are not alone.

Often people who are deep in debt, are more afraid to confront the reality of their situation than anything else. That fear can lead people to do things they never thought they would do: to stop opening their mail, to stop answering the phone for fear of dealing with bill collectors, or even to lie to their family and friends.

It is important to understand that you are not alone. You are not the first person to go through a crisis and there are resources out there to help you.

To read about how even an economic reporter fell into the trap of overusing credit check out this New York Times article: http://tinyurl.com/qukwpb.
Related Posts Plugin for WordPress, Blogger...