Wednesday, September 5, 2012

The Student Loan Problem (Infographic)

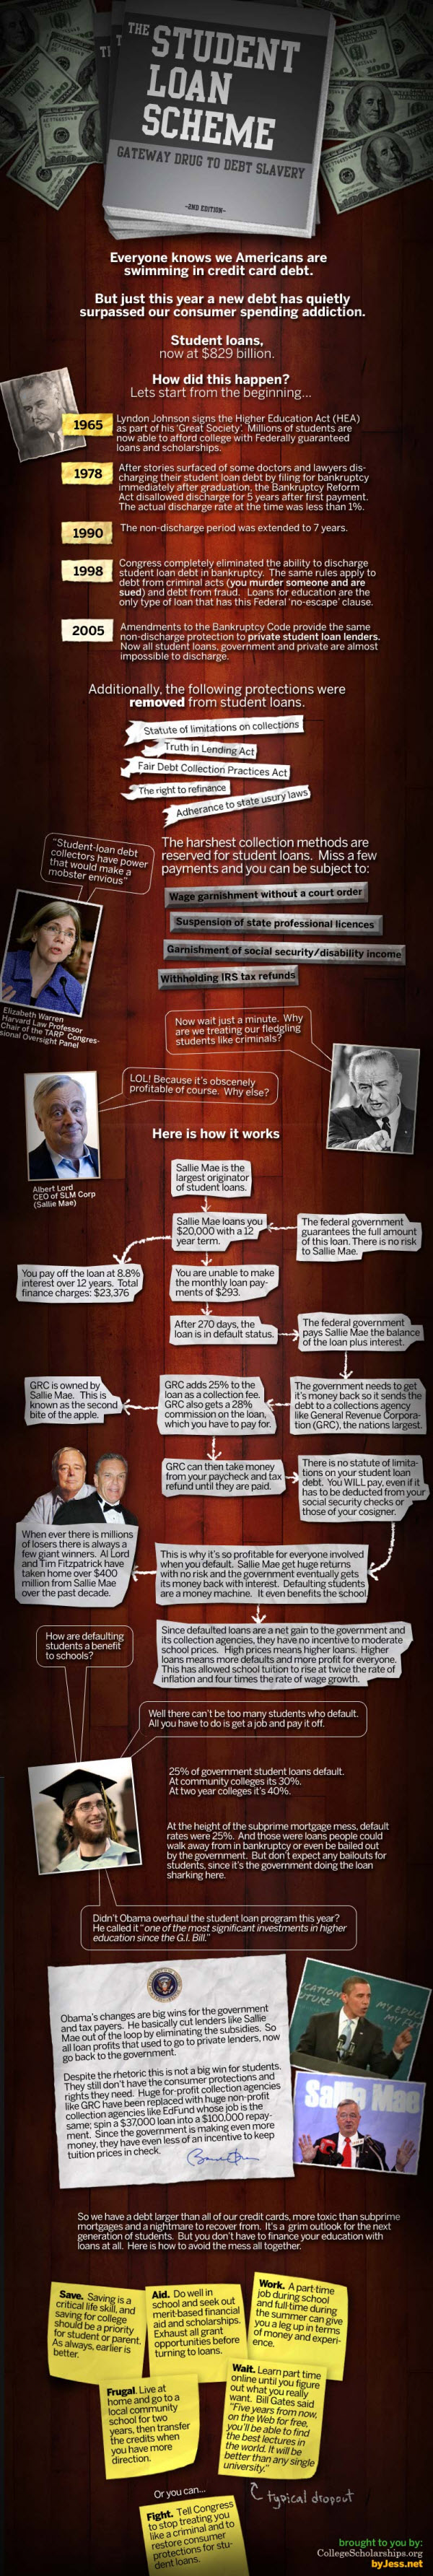
The following infographic provides an overview of the student loan problem in America, how we got here, and why it is getting worse:

Student Loans Scheme.
Infographic by College Scholarships.org

Reprinted from: College Scholarships.org

Kelsey & Trask, P.C. provides this graphic for informational purposes only. We do not endorse nor claim endorsement from the source site or organization. Kelsey & Trask, P.C. is not responsible for any information contained therein, unless indicated specifically on that site.

Thursday, July 19, 2012

How important is my Credit Score?

Back in June, Attorney Trask spoke on a panel to address some of the public’s concerns regarding divorce, short sales, foreclosures and bankruptcies. The other members of the panel included a financial advisor and a mortgage broker. Of particular concern to the attendees was the harm to someone’s credit that could be caused by bankruptcy, foreclosure, or falling behind on payments on any number of consumer debts an individual may have.

The mortgage broker’s point was stark: “you are your credit score”. The observation garnered some mumbling from the crowd, but the point was clear: In the current economy where the cost of living exceeds an individual’s ability to save for a major (and necessary) purchase like housing, the only practical way for “the 99%” to acquire housing is to rent or purchase with a mortgage from a bank. However your ultimate ability to do so often comes down to a three-digit number maintained by any number of credit reporting bureaus.

A credit bureau is a private business that sells information – nothing more. The information that they sell is data reported to them by your creditors for things such as account and payment history, balances, late payments, and available credit. That information is churned through an algorithm to determine your “creditworthiness” and is expressed as a number. Depending on the agency, the scores can vary, but generally, a FICO credit score ranges between 300 and 850; a VantageScore score ranges from 501-990.

Your credit score is essentially a measure of your financial health that banks and other lenders use these scores to measure eligibility for mortgages, credit cards and a wide variety of other consumer loans. Some landlords check them to screen prospective renters, and some companies check credit reports before hiring a new employee. Low scores or problematic credit histories can mean higher interest rates or rejected applications.

Despite the importance that fair and accurate credit history reporting holds on an individual’s ability to obtain housing, employment, or other consumer loans, the various credit reporting agencies were under fairly lax legislative oversight. The Fair Credit Reporting Act required that all information contained in a report be “accurate”, but did little to specify any procedure to ensure accuracy. The FCRA primarily provides a mechanism to disclose the information contained in the report to a consumer – not to redress inaccuracies in the report itself. A consumer is entitled to a free credit report (but not a free credit score) within 60 days of any adverse action (e.g. being denied credit, or receiving substandard credit terms from a lender) taken as a result of their credit score.

However, there seems to be some change on the horizon.

In addition to the Fair Credit Reporting Act, Under the Wall Street Reform Bill passed on July 22, 2010, a consumer is entitled to receive a free credit score if they are denied a loan or insurance due to their credit score. Also, the newly-created U.S. Consumer Financial Protection Bureau (CFFB) has indicated an intention to provide additional federal oversight of credit reports in an effort to ensure accuracy, and will be able to conduct an investigation of the offending reporting agency in the event of a consumer complaint. These changes were discussed in our previous post as well:  Is the Government Monitoring your Credit Report?


Tuesday, July 17, 2012

Is the Government Monitoring your Credit Report?

Yesterday afternoon, the lead headline at DrudgeReport.com was that the U.S. Government is going to begin Monitoring Credit Reports. It would appear that, in typical Drudge style, the headline sought to create fear and distrust, implying that the government was concerned about who you were borrowing money from. This particular article remained up for only a short time, and was quickly taken down to address the more urgent matter: Democrats plan to use Batman Against Romney

An in-depth review of the Credit Report Article would suggest a more benign use of the new U.S. Consumer Financial Protection Bureau (CFFB). According to CFFB director Richard Cordray, beginning on September 30, 2012, the bureau seeks to extend oversight of the 30 largest credit reporting bureaus, which make up about 94% of the credit reporting industry in the United States. Such oversight would help ensure the accuracy of information contained in the reports, provide redress for individuals who have fallen victim to inaccurately-reported information, and provide “clarification as to what the Fair Credit Reporting Act requires of credit bureaus”.

Such an overhaul of the regulatory oversight would seem appropriate, given the importance of credit scores in today’s economy. Banks and other lenders use these scores to measure eligibility for mortgages, credit cards and a wide variety of other consumer loans. Some landlords check them to screen prospective renters, and some companies check credit reports before hiring a new employee. Low scores or problematic credit histories can mean higher interest rates or rejected applications.

A more accurate headline for Drudge to use would have been the actual headline: Consumer bureau to police credit reporting bureaus.  Given the immense power the credit bureaus have over your finances based on how they report your information, perhaps this is a good thing (inasmuch as any further government regulation can be a good thing).


Monday, July 9, 2012

US Trustees Release New Figures for Median Family Income


The United States Department of Justice twice per year releases new Median Family income figures for each state and territory.  These figures are used to calculate a debtor's eligibility to file for bankruptcy under Chapter 7 of the Bankruptcy Code. If your income is greater than the median income for your state of residence and family size, in some cases, creditors have the right to file a motion requesting that the Court dismiss your cases under Section 707(b) of the Bankruptcy Code.

It is ultimately up to the Bankruptcy Judge to decide whether the case should be dismissed. However, if your income exceeds the median family income then a presumption arises under part (a) of the Means Test that you do not qualify for a chapter 7 bankruptcy.

The Means Test calculation compares your average monthly income (as calculated over the last six (6) months) to the median family income in your state for a household of your size. If your average monthly income is lower than the median family income for your state of residence and family size, then you meet the means test and there is a presumption that you may file for Chapter 7 relief.

If your income is greater than the median income for your state of residence and family size, you still might meet part (b) of the means test after taking into consideration certain expenses as defined by the Bankruptcy Code and other deductions, including regular charitable donations (up to 15% of your income), school expenses, payments on 401(k)/IRA loans, and health Insurance.  If you are subject to this calculation an attorney can help you perform this task.

The Median Family Income for Massachusetts as of November 1, 2011 were as follows:

Family size 1: $53,496 per year
Family size 2: $64,174 per year
Family size 3: $80,337 per year
Family size 4: $99,067 per year

add an additional $7,500 per year for each additional household member.

These figures went up approximately $2,000 per category per year on May 1, 2012.

The Median Family Income for Massachusetts as of May 1, 2012 are as follows:

Family size 1: $55,185 per year
Family size 2: $66,200 per year
Family size 3: $82,873 per year
Family size 4: $102,194 per year

add an additional $7,500 per year for each additional household member.

Click here to learn more about The Means Test or use our Means Test Calculator.

To have an attorney help you with these calculations call 508.655.5980 to schedule a consultation or e-mail us here.


Friday, June 8, 2012

My creditor has placed a lien on my house. Will the lien be discharged in bankruptcy?

When a debtor files for bankruptcy and receives a discharge, the Order Discharging Debtor will absolve the debtor of all dischargeable debts, and bar creditors from collecting those debts from the debtor in the future.

However, certain creditors can file a lien against property (usually real property) to ensure that their loan is paid. If your creditors have recorded liens against your property, the discharge order will not automatically discharge those liens. In certain cases, it is possible to avoid the lien (i.e., strip off the lien), but your bankruptcy attorney must file a motion to do so. Certain liens are not avoidable, such as liens given with your consent and tax liens) and will remain on the property. The most common example of an unavoidable lien is your typical mortgage.

Most people are familiar with the legal relationship between a borrower and a lender in the context of a mortgage – a bank lends money to someone wishing to purchase a home, and in exchange for the loan and the borrower’s promise to repay the debt, the lender places a lien against the property granting them certain rights, including the right to foreclose if the debtor does not honor the terms of the borrower’s obligation to repay. This arrangement protects the lender by giving them legal recourse against the collateral, so that they can recoup all or a portion of their loan if the borrower fails to pay.

A lien arising out of a mortgage is not avoidable because it is “voluntary”. Here, the borrower allowed the lender to place a lien on his or her property (or pledged some other collateral) in exchange for something of value, such as a loan. Voluntary liens are not avoidable in bankruptcy pursuant to the U.S. Bankruptcy Code. Although the borrower can never pursue the discharged debtor for any deficiency, in order to pass clear title to the property upon sale, the lien must either be paid by the new buyer or discharged (i.e., forgiven) by the lender.

In addition, liens placed against property by government institutions for taxes are not avoidable in bankruptcy.

In certain cases, however, a creditor may have obtained a lien against your property against your will. The most common is a judicial lien, in which a creditor has taken you to Court for an unpaid debt, obtained a judgment in their favor, and requested a sheriff to “execute” that judgment against your property. A copy of the judgment would be recorded in the registry of deeds in your county against your property. As before, even if the underlying debt is discharged in bankruptcy, the lien obtained by the creditor remains in place. The debt does not have to be repaid by virtue of the discharge, but the lien will continue to cloud the title to the property, making a future sale difficult or impossible if the lien is not paid at closing.

11 U.S.C. § 522(f) permits a debtor to remove liens based on a legal judgment of a nonpriority creditor – to the extent the lien encumbers the value of the debtor’s exemption(s) in the property. Put another way, if the value of the debtor’s equity in the property would be exempt even without the encumbering lien, a court, on motion of the debtor, may avoid the lien, effectively stripping it from the title history of the property.

The procedure for avoiding a judicial lien varies from state to state, and must be made by motion to the court. If any of your creditors have obtained a legal judgment against you, and recorded that judgment as a lien against your property, simply filing for bankruptcy isn’t enough. Ensure that your bankruptcy attorney is aware of the existence of the lien, and they will be able to advise you as to whether it can be avoided, and if so, file the appropriate motion with the Court.

Tuesday, June 5, 2012

Learning to Fly and Bankruptcy Exemptions


I would like to lean to fly. Not in a superman sense – in a “small aircraft” sense. As the first step in achieving that goal, this past weekend, I took a flying lesson and had a great time. When I was done, I was mulling over the legal ramifications of aircraft ownership, and as my legal mind started to wander, I pondered how the ownership of an aircraft would be handled in a bankruptcy. While this may not be where your mind would have wandered, consider it an occupational hazard of being a bankruptcy attorney. I don’t want you to get the wrong impression, but when you are a bankruptcy attorney, you sometimes can’t help but look at the world through a proverbial “bankruptcy filter”.

Since not everyone wants, or owns, an airplane, writing an answer to “how would a small aircraft be treated in bankruptcy” might seem somewhat superfluous. In fact, the rest of the people in my office would no sooner get into a small plane as they would shave their head. But what occurred to me is that nearly everyone has their “learning to fly.”

In good financial times, most of us purchase “toys” or other items that support our hobbies, but what happens when the same folks may be facing bankruptcy? If selling the toys and paying the debt is not an option, how are these items treated in bankruptcy? The “toys” could be anything: aircraft, boats, motorcycles, or classic cars. Maybe motors aren’t your thing, but you have a nice collection of high-end computers and electronics. If you spend your Sundays working in a wood shop, woodworking equipment or other tools might be your “toys”.

How are these hobby items treated in bankruptcy?

Like any other asset, the item you seek to protect must be disclosed to the bankruptcy court (along with all other assets) and are subject to acquisition by the trustee if they are not exempt under the Federal or Massachusetts exemptions. There are a number of exemptions that may be used to establish the exemptability of items. Ultimately, the amount of the allowable exemptions may be affected by the debtor’s desire to exempt other personal property, but generally speaking, the following exemptions are available to protect a debtor’s items which do not fall into a specific exemption category (such as jewelry, certain religious articles or motor vehicles, which are discussed later on):

Federal Exemptions:

11 U.S.C. § 522(d)(5): $1,150.00, which is federal catch-all exemption and may be applied to any personal property owned by the debtor;

11 U.S.C. § 522(d)(5): Up to $10,825.00 of unused home equity not already exempted under 11 U.S.C. § 522(d)(1);

11 U.S.C. § 522(d)(6): $2,175.00 for tools and equipment used in business. For this exemption to be applicable to the debtor, the debtor must establish that the items are necessary for the debtor’s trade, employment or business.

Massachusetts Exemptions

A debtor filing for bankruptcy in Massachusetts may elect either the Federal exemptions or the Massachusetts exemptions. Massachusetts exemptions applicable to firearms ownership are as follows:

M.G.L. c. 235 § 34(5): $5,000.00 for tools and equipment used in business. Like the federal exemptions, for this exemption to be applicable to the debtor, the debtor must establish that the items are necessary for the debtor’s trade, employment or business. Therefore, if the items are used in the debtor’s business or money-making efforts, they may be exempt up to $5,000.00, regardless of their less intrinsic value as hobby items to the debtor.

M.G.L. c. 235 § 34(17): Up to $6,000.00, representing the debtor’s aggregate interest in any personal property, not to exceed $1,000 in value, plus up to $5,000 of any unused dollar amount of the aggregate exemptions provided for the exemption of household furnishings, tools of the trade and a motor vehicle.

Special Considerations for Motor Vehicles

In Massachusetts, you can exempt up to $7,500 in equity in one car or other vehicle that you use for personal transportation or to find or maintain employment. If you are 60 years of age or older, or if you are disabled, you can exempt up to $15,000. If you decide to use the federal bankruptcy exemptions, you can exempt up to $3,450 of equity in your motor vehicle. The law does not care if your one primary vehicle is a 2005 Honda Civic, a 2012 Harley-Davidson Dyna Super Glide or a 1969 Yenko Camaro; only the amount of the debtor’s equity in the vehicle matters.

If the item you seek to protect is a registered motor vehicle, but not your primary mode of transportation, some trustees will disallow an exemption claimed under either the federal or Massachusetts “motor vehicle” exemptions. Additionally, although the Massachusetts exemption laws specifically state “automobile”, many trustees will not object to the debtor’s attempt to discharge a motorcycle if it is your primary mode of transpiration.

So, what does this all mean?

It means that the answer to the original question is “it depends”. The ability to exempt hobby items largely turns on the value of the item, and the other expemptions already claimed by the debtor for such necessities as their home, household goods and furnishings, or employment-related tools. In a “perfect storm” of circumstances, you may be able to exempt upwards of $20,000 of equity in your “toys”, but the real value depends on the totality of circumstances in your bankruptcy case.

If you are facing bankruptcy and have personal and other property, such as a home and retirement accounts that you want to ensure is protected through the bankruptcy process, contact Attorney Matthew P. Trask to learn more about how to protect your assets and find your financial freedom.

Thursday, May 31, 2012

I am the primary borrower on a loan and my cosigner has filed for bankruptcy. What should I do to protect myself?

A co-signer is an individual who is promising to repay a loan in the event the primary borrower defaults. In many cases, having a co-signer on a loan may have been necessary to obtain the loan because the primary borrower’s credit rating was insufficient to qualify on their own, and the co-signer stepped in to assist the primary borrower to obtain financing.

As we discussed in our previous post, if the primary borrower defaults (or files bankruptcy), the co-signer will be required to pay the loan back. But what about the reverse situation?

How is the primary borrower affected if the cosigner files for bankruptcy?

Consider the same example: Adam wants to buy a car, but can only qualify for a loan with a co-signer. Betsy agrees to co-sign, but her name is not listed on the title as an owner of the vehicle. This time Betsy files for bankruptcy and obtains a discharge of the car loan. For the sake of simplicity, we will assume that Betsy has no ownership in the vehicle that may be attributed to her by the Trustee.

Adam is still legally obligated to repay the unpaid balance of the loan. However, when Adam pays off the loan, all liens will be released, and the title will be issued in Adam’s name. Most auto financing agreements make no distinction between the “borrower” and “co-borrower” aside from whose name the title will ultimately be issued to. As such, the bankruptcy of a co-borrower is similarly a breach of the terms of the loan, and could result in a default under the terms of the note. As before, the bankruptcy (and discharge) of the co-borrower’s obligation leaves the lender in a position where they can only pursue one individual, not two, in the event the loan is not paid.

This material departure from the original agreed upon terms could be considered a default, and in fact, many auto financing agreements specifically include such a term. However, it has been my experience that the lender will receive a greater financial return by accepting the primary borrower’s monthly payments than they would by repossessing the vehicle and selling it at auction, meaning that the primary borrower will likely keep the vehicle, despite the co-borrower’s bankruptcy.

In the event a co-borrower files for bankruptcy, the best thing that the primary borrower can do is seek to refinance the balance on the car loan, if possible. Many credit unions and some larger banks offer automobile refinancing loans. By refinancing the loan, the primary borrower has effectively paid off the loan securing the vehicle, and negated any circumstances which could trigger a default. If handled properly, and for a qualified borrower, it is often possible to keep payments the same, or even lower payments upon refinancing the car.

A borrower may be tempted to sign a reaffirmation agreement presented by the lender. However, executing the reaffirmation agreement is, in my opinion, not a legal guarantee that the bank will take no further action, nor will it cure any default under the terms of the note upon the co-borrower’s filing for bankruptcy. First, in order to cure the issue of default, at a minimum, the co-borrower filing for bankruptcy would have to sign. A reaffirmation agreement is an agreement arising in the context of a bankruptcy case. Here, the primary borrower is not seeking bankruptcy protection, nor is he electing to “remove” the debt from the discharge order; and therefore the primary borrower, Adam in our example above, has no standing to sign the reaffirmation agreement.

The bankruptcy of a co-borrower should not appear on Adam’s credit report, but because some lenders will automate their reports to credit agencies, there is a reasonable likelihood that the entry may make some indication of bankruptcy. If this happens, the information in the credit report is incorrect. It may be necessary to contact the three credit bureaus (Equifax, Experian, and Trans Union) as well as the lending institution to ensure that this information is correctly reported on the primary borrower’s credit report. Again, refinancing with a new loan is the simplest way to resolve this issue because then the loan will be listed as paid, and the new loan will report positively on a credit report (as long as you continue to pay it on time).

As with the decision to co-sign a loan, the decision to obtain a loan requiring a co-signer comes with significant legal consequences if the co-signer does not honor the terms of the note. Consider the need to take out a loan with a co-signer carefully, and if the co-signer files for bankruptcy , it may be worth your while to reach out to a bankruptcy attorney to better understand your options and obligations regarding the loan.

Related Posts Plugin for WordPress, Blogger...